VA Loans
VA Jumbo Loan Limits Near Savannah in 2026
Quick answer
With full VA entitlement there is no VA loan limit; the lender sets the maximum based on income, credit and debts, up to the appraised value or the purchase price, whichever is lower. County limits apply only to remaining entitlement. In 2026 the limit is $832,750 in Chatham, Effingham, Bryan, Liberty and Bulloch counties.
This page answers one question: how far up in price a VA loan can go. The short answer is that VA sets no maximum for a veteran with full entitlement, and the reason is in the guaranty math rather than in any loan limit.
I'm a licensed real estate agent, not a lender. Nothing here is a loan approval or a statement about your file. Every figure below is cited so you can check it.
Is there a VA loan limit in 2026?
Not for a veteran with full entitlement. Since 2020, VA has not applied county loan limits to borrowers with full entitlement (opens in a new tab), so the lender decides how much it will lend (opens in a new tab), up to the appraised value or purchase price, whichever is lower (opens in a new tab).
For a home purchase loan over $144,000, 38 U.S.C. § 3703(a)(1)(A)(i)(IV) (opens in a new tab) caps the guaranty at 25 percent of the loan, or at the veteran's available entitlement if that is less. For a veteran who is not a "covered veteran," § 3703(a)(1)(C)(i) (opens in a new tab) sets the maximum guaranty entitlement at 25 percent of the loan. That clause names no dollar ceiling. The guaranty scales with the loan instead of stopping at a number.
There is still a ceiling, it is just not one VA sets. In VA's words (opens in a new tab), "The maximum VA loan on an individual property is either the appraised value of the property or the purchase price, whichever is lower." And a lender still has to approve you, based on credit history, income, debts and assets, per the same VA loan limits page (opens in a new tab).
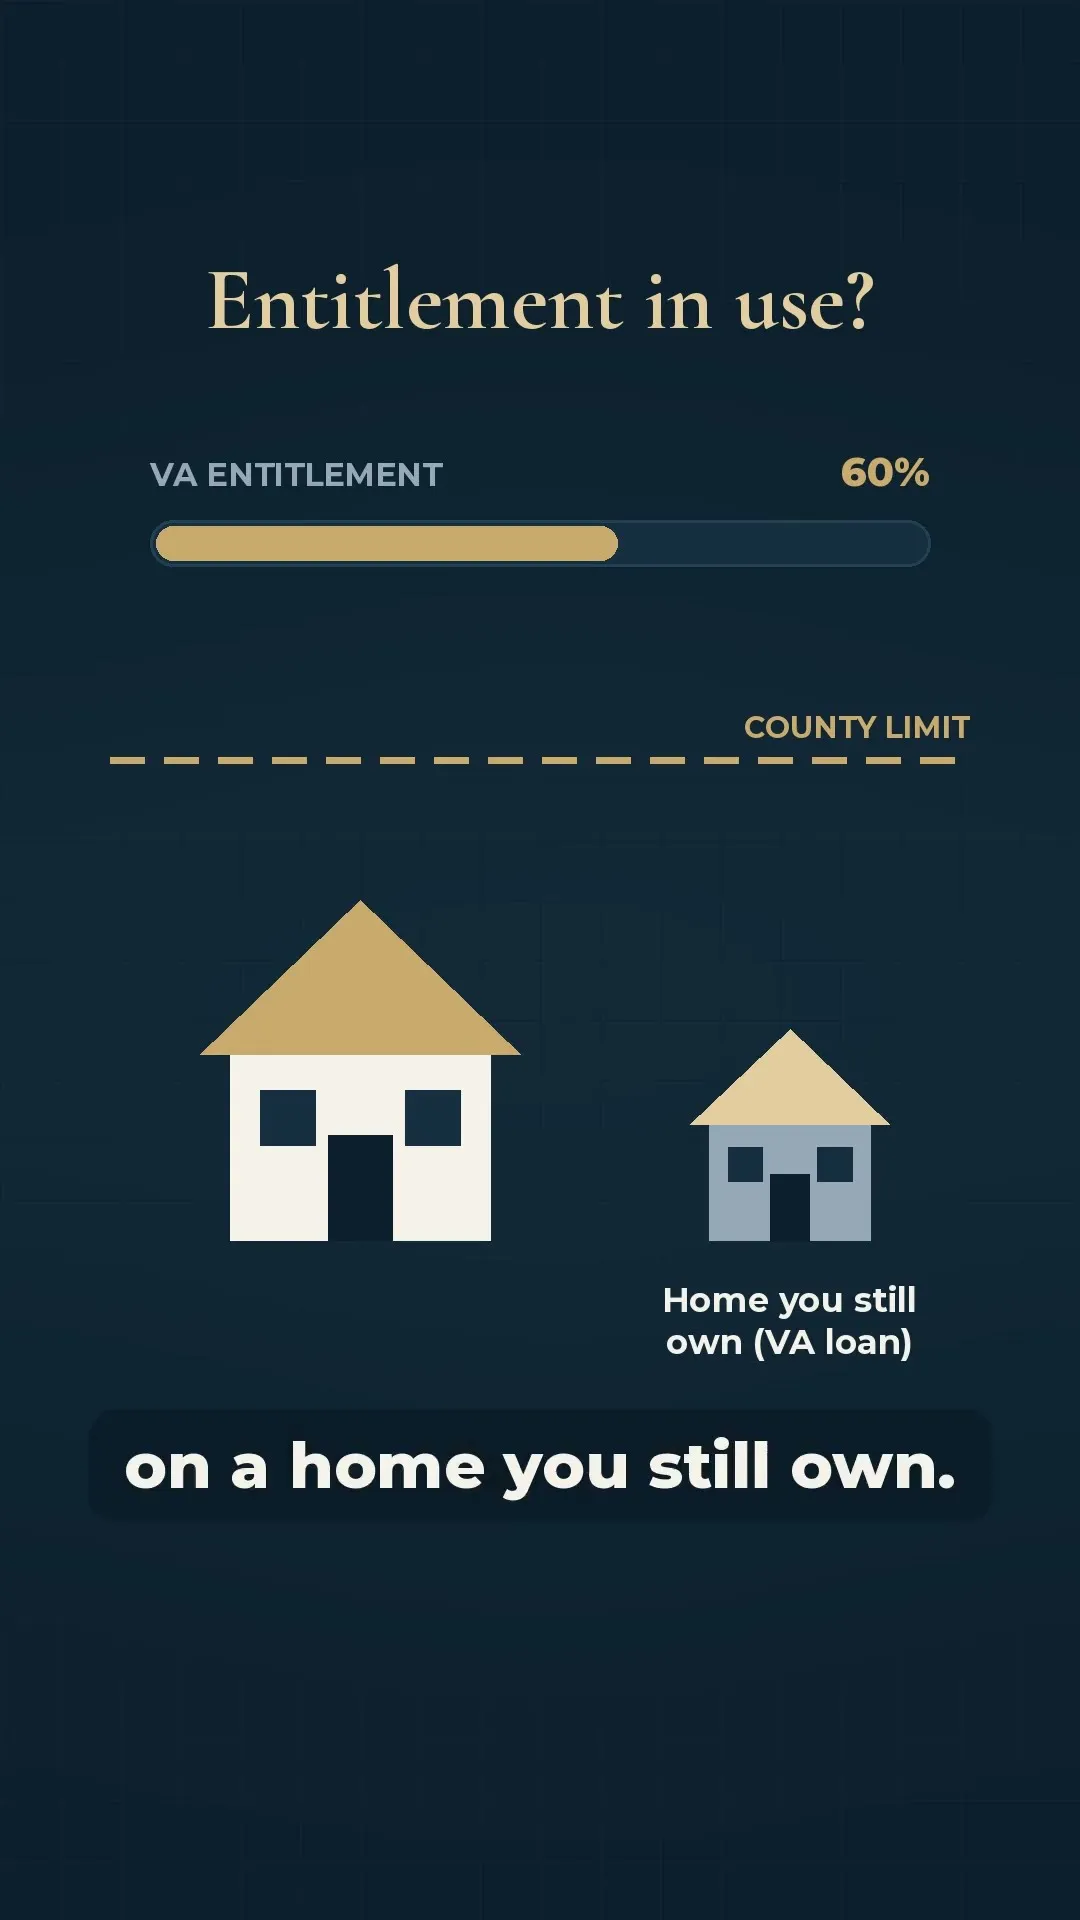
Does the VA have a loan limit? (2026, Savannah GA)
For a lot of veterans, no. With full VA entitlement, there's no VA loan limit. Your lender decides how much you can borrow, based on your income, credit and debts. The county limit only applies if part of your entitlement is already in use, like a VA loan on a home you still own.
Read the transcript
Does the VA have a loan limit? For a lot of veterans, no.
If you have your full VA entitlement, there’s no VA loan limit.
Your lender decides how much you can borrow, based on your income, credit and debts.
The county limit only comes into play if part of your entitlement is already in use, like a VA loan on a home you still own.
Around Savannah, the 2026 limit is $832,750 in Chatham, Liberty, Bryan, Effingham and Bulloch counties.
If you go above what your remaining entitlement covers, you may need a down payment.
Your lender can run the exact numbers for you.
I’m Scotty Parrish with Next Move Real Estate.
What is the 2026 VA loan limit near Savannah?
For a veteran using remaining entitlement, the 2026 county loan limit is $832,750 for a one-unit property in Chatham County, Effingham County, Bryan County, Liberty County and Bulloch County, per FHFA's 2026 county list (opens in a new tab). Every Georgia county in that list is at the same figure. A veteran with full entitlement has no VA loan limit in any of them.
| County | 2026 one-unit limit |
|---|---|
| Chatham | $832,750 |
| Effingham | $832,750 |
| Bryan | $832,750 |
| Liberty | $832,750 |
| Bulloch | $832,750 |
VA uses the same one-unit county limits as FHFA. (opens in a new tab) Sources: FHFA's announcement of the 2026 conforming loan limit values (opens in a new tab) and VA's loan limits page (opens in a new tab).
Limits verified from FHFA's 2026 county list (opens in a new tab).
When does the county loan limit apply?
Only when part of your entitlement is already in use (opens in a new tab) and you are working from remaining entitlement. It applies to some borrowers and not to others.
At § 3703(a)(1)(C)(iii)(I) (opens in a new tab), the statute defines a covered veteran as one "who has previously used entitlement under this chapter and for whom the full amount of entitlement so used has not been restored as a result of the exclusion in section 3702(b) of this title."
For a covered veteran, § 3703(a)(1)(C)(ii) (opens in a new tab) caps the maximum guaranty at 25 percent of the Freddie Mac conforming loan limit, reduced by entitlement already used and not restored. The statute ties that limit to the limit for a single-family residence under 12 U.S.C. 1454(a)(2), "as adjusted for the year involved."
For 2026, FHFA set the one-unit baseline at $832,750 (opens in a new tab), with a ceiling of $1,249,125 in high-cost areas, announced November 25, 2025. For 2026, Chatham, Effingham, Bryan, Liberty and Bulloch counties are all at that $832,750 baseline, per FHFA's 2026 county-level conforming loan limit list (opens in a new tab).
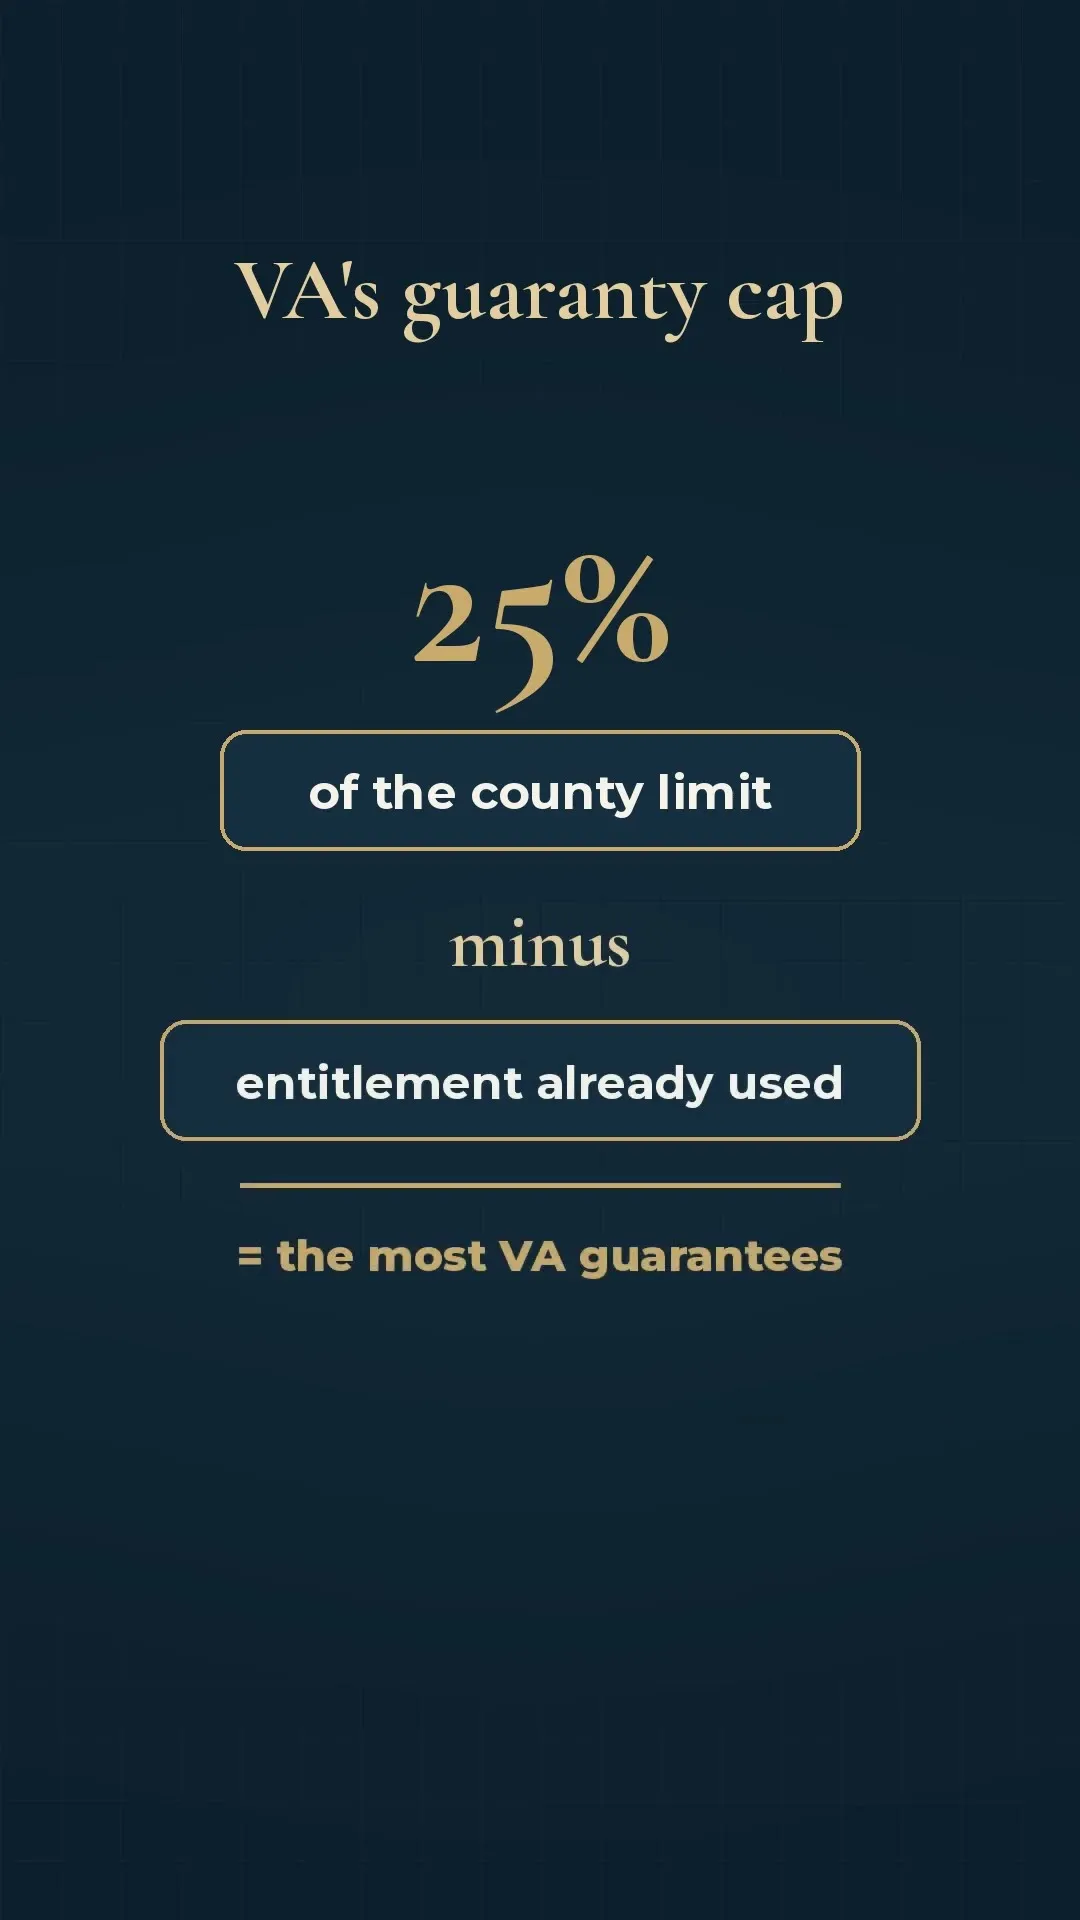
Remaining VA entitlement explained (2026, Savannah GA)
Still have a VA loan on your last home? Then you're working with remaining entitlement, and the county loan limit comes back into the math. VA's guaranty is capped at 25 percent of the county limit, minus the entitlement you've already used.
Read the transcript
Still have a VA loan on your last home? That's where remaining entitlement comes in.
If you've used entitlement and it hasn't been restored, the county limit comes back into the math.
VA's guaranty is capped at 25 percent of the county limit, minus the entitlement you've already used.
Around Savannah, that limit is $832,750 for 2026.
Your lender uses what's left to figure the most they'll lend without a down payment.
So two veterans can look at the same house and get different answers.
Your lender and VA can confirm where you stand.
I'm Scotty Parrish with Next Move Real Estate.
An illustration: remaining entitlement on a $700,000 home
The numbers below are an illustration, not anyone's real file. Your lender confirms the real numbers from your Certificate of Eligibility, which shows the entitlement you have already used (opens in a new tab).
The scenario: a veteran still owns a home with an open VA loan of $200,000, and $50,000 of entitlement is used on it. The veteran is buying a $700,000 home in Chatham County in 2026, and the appraisal comes in at $700,000 or more. The steps follow VA's method for working out remaining bonus entitlement (opens in a new tab). The VA funding fee is left out.
| Step | How it is worked out | Amount |
|---|---|---|
| 2026 county loan limit, Chatham County | FHFA's one-unit limit | $832,750 |
| 25 percent of the county limit | $832,750 times 0.25 | $208,187.50 |
| Entitlement already used | From the Certificate of Eligibility | $50,000 |
| Remaining guaranty | $208,187.50 minus $50,000 | $158,187.50 |
| Most lenders' maximum loan with no down payment | $158,187.50 times 4 | $632,750 |
| Amount above that | $700,000 minus $632,750 | $67,250 |
| Down payment most lenders require | 25 percent of $67,250 | $16,812.50 |
The check: the $158,187.50 guaranty and the $16,812.50 down payment together come to $175,000, which is 25 percent of the $700,000 price. VA's Buyer's Guide (opens in a new tab) says: "Most lenders require a combination of the guaranty entitlement and any cash down payment to equal at least 25 percent of the appraised value or sales price of the property, whichever is less." The $632,750 figure is from VA's loan limits page (opens in a new tab), which calls remaining bonus entitlement times four "the maximum amount most lenders would be willing to loan you without your needing to make a down payment."
Do I need a down payment on a VA jumbo loan?
It depends on your entitlement, and the lender makes the call. With remaining entitlement, a down payment may be needed on a larger loan (opens in a new tab), and your lender can show you the exact math.
VA's loan limits page (opens in a new tab) says: "A lender will use your remaining bonus entitlement to determine the maximum amount they'll loan you without requiring a down payment." So two veterans can look at the same house and get different answers about a down payment, depending on whether entitlement was used before and whether it came back. Which of those you are is a question for your lender and for VA.
Does the funding fee get bigger on a large loan?
The fee is a percentage, so it scales with the loan amount. That makes the exemptions worth knowing about at this end of the market more than at any other.
VA's funding fee schedule (opens in a new tab) for purchase and construction loans, for Veterans, active-duty members, and Guard and Reserve members: first use, 2.15 percent with less than 5 percent down, 1.5 percent at 5 percent or more, 1.25 percent at 10 percent or more. Subsequent use: 3.3 percent with less than 5 percent down, then the same 1.5 and 1.25. These rates took effect April 7, 2023. VA publishes these rates and they change, so confirm them before you rely on them.
You owe no funding fee at all if any of the following is true, in VA's own wording (opens in a new tab):
- "You're receiving VA compensation for a service-connected disability"
- "You're eligible to receive VA compensation for a service-connected disability, but you're receiving retirement or active-duty pay instead"
- "You're receiving Dependency and Indemnity Compensation (D.I.C.) as the surviving spouse of a Veteran"
- "You're a service member who has received a proposed or memorandum rating before the loan closing date that says you're eligible to get compensation because of a pre-discharge claim"
- "You're an active-duty member of the Armed Forces, and on or before your loan closing date you provide evidence that you received a Purple Heart"
There is also no monthly mortgage insurance. VA's funding fee page (opens in a new tab) says the program doesn't require "monthly mortgage insurance."
For the whole fee, including how it is paid and refunds, see VA Funding Fee Explained.
Where to take it from here
For a buyer with full entitlement, and as long as the loan amount does not exceed the appraised value, VA's own quick reference for real estate professionals (opens in a new tab) says "jumbo loans of over $1 million are possible for eligible and qualified borrowers with VA home loan lenders who offer them." Whether that describes your situation is a question for your lender and for VA.
What I can tell you is how a VA offer is written so that it holds up. What you can borrow is not something a website can answer, and I would not trust one that claimed otherwise.
Frequently asked questions
Does the VA set a maximum loan amount?
VA sets none for a veteran with full entitlement, but the loan is still limited by the appraisal or the price, and by what a lender will approve.
What counts as remaining entitlement?
It is what is left when you have used entitlement before and not all of it has been restored. For that borrower, the statute (opens in a new tab) caps the guaranty at 25 percent of the conforming loan limit, less the entitlement already used and not restored.
Are any Georgia counties above $832,750 in 2026?
No. Every Georgia county in FHFA's 2026 county list (opens in a new tab) is at $832,750 for a one-unit property.
Who sets the county loan limits?
FHFA does, each year, and VA uses the same one-unit county limits (opens in a new tab). FHFA announced the 2026 figures on November 25, 2025 (opens in a new tab).
Sources
- FHFA news release, November 25, 2025: FHFA Announces Conforming Loan Limit Values for 2026 (opens in a new tab), checked
- VA.gov: VA home loan entitlement and limits (opens in a new tab), checked
- FHFA's 2026 county list of conforming loan limits (opens in a new tab), checked
- 38 U.S.C. § 3703, at Cornell's Legal Information Institute (opens in a new tab), checked
- VA.gov: VA's funding fee page (opens in a new tab), checked
- VA's quick reference for real estate professionals (opens in a new tab), checked
- VA Home Loan Guaranty Buyer's Guide, April 2022 (opens in a new tab), checked
VA rules and the conforming limit both change. The date each source was last checked is beside it in the list above.
Scotty Parrish
Questions about this property or this market? I answer these directly.
Start a Private Conversation